Households hoping that the Bank of Canada will cut interest rates to passively improve their existing debt have been waiting for half a year, and there is still no definite timetable. Whether and how much interest rates will be cut in 2024 is still unknown. At the same time, 16% of Canada’s existing mortgage loans will expire in 2024, and interest rates and monthly payments must be reset. Households with large existing debts and those facing mortgage renewal this year can engage in active debt management in addition to passively waiting for the central bank to cut interest rates. In the past six years, I have promoted many active debt management methods through this official account. Attentive readers can summarize and summarize them from previous articles. This article will also briefly summarize the three most common methods of active debt management.
01 Make good use of cash in hand
Using cash on hand to reduce debt is a very instinctive approach and should not be a debt management skill. However, in practice, many households use cash unwisely.
The first principles of using cash on hand to deleverage are:The preferred use of cash is to accelerate the repayment of owner-occupied loans, not rental housing loans.The core content of household debt management is to make daily efforts to reduce consumer debt, including student loans, car loans, credit card loans, and home loans.There is no need to accelerate repayment of rental housing loans, because rental housing loans are investment loans, and the interest is tax-deductible. As long as the cash flow can be sustained, even if all consumer debts are paid off, the family will still have excess cash, and there is no need to accelerate the repayment of the rental housing loan, unless there is a serious cash flow crisis.
Families with cash in hand may consider accelerating the monthly repayment of investment properties if the prepayment limit for their home has been exhausted and there will be fines for paying more, which is the most stressful situation. Accelerating repayment can reduce the monthly housing debt. The reason why we need to remind everyone of this is because some banks, while providing "negative amortization" floating interest rate repayment methods, also continue to urge borrowers who "enjoy" this facility to give up using this facility. Borrowers were urged over and over to voluntarily give up this facility, and the letters hinted at the disadvantages of using these facilities. Families with cash on hand may not be able to withstand these urgings and use their precious cash to accelerate the repayment of investment housing loans, thereby reducing the interest expenses of investment housing, in disguise, increasing the net income of investment housing and increasing taxable income. For a loan that starts to have negative amortization, even if you use cash to accelerate repayment, the monthly payment may not be reduced. Therefore, it is not recommended to accelerate the repayment of a mortgage with negative amortization. It is always a bad idea to use the cash on hand to accelerate the repayment of investment housing loans. Unless your family's cash flow has serious problems, there is no need to accelerate the repayment of investment housing debts, no matter how eager the bank uses to induce you.
If a household without cash encounters a debt crisis, its first choice is to sell financial assets rather than real estate. When selling a property, if the property appreciates significantly, a huge capital gains tax will be incurred. While solving this year's cash flow crisis, it will dig a big hole for next year's tax filing. When selling a property, if the value does not appreciate much, potential buyers will consider it to be a cash flow crisis, so they will suffer deep price cuts and the property will be difficult to sell.Selling a house for cash is killing the goose that lays the eggs, and is a last resort.
The majority of realizable financial assets among Canadian households are U.S. stocks or bonds. When there is a crisis in household debt, if financial assets need to be liquidated, the first choice is the financial assets that have been profited in the TFSA account. For example, borrowers who renewed their contracts between August and November last year all had fixed interest rates above 7%. If the loan balance is large and the monthly payment after renewal is very high, you can consider selling the profitable financial assets in the TFSA account to accelerate the repayment of the loan principal when the contract expires, thereby avoiding excessive monthly payments affecting the overall household debt level. Thanks to the U.S. stock market, which has been rising steadily over the past two years, families in debt crisis have seen a glimmer of light.
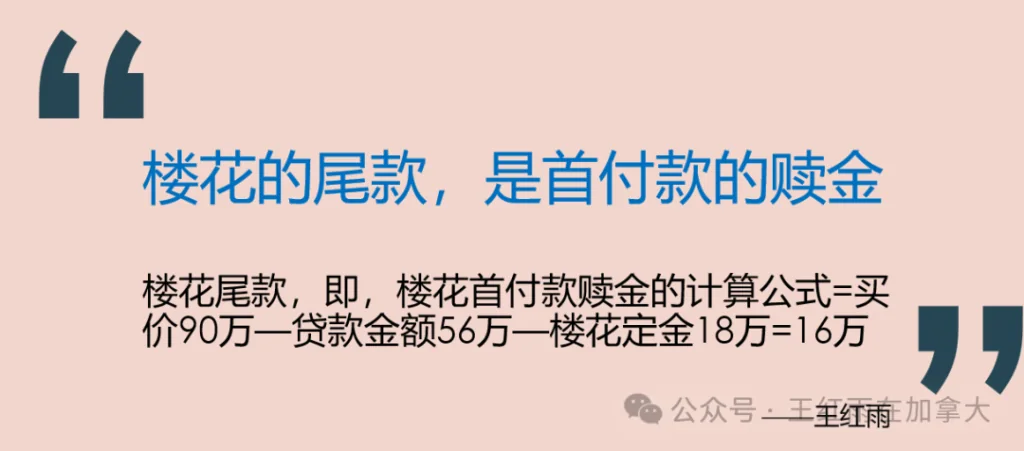
Families with too much cash on hand are not within the scope of this article, but readers need to be reminded that based on the current status of the off-the-plan property market, do not use cash to buy off-the-plan properties. At certain times, the cash deposited for the off-the-plan property eventually becomes a kind of kidnapping of the cash."The balance of the off-plan property is the ransom of the down payment" - Henry Wang. The cash you put in today may require a ransom to be released when the house is handed over, so don't let your cash be kidnapped. The current handover situation of the off-plan property is shocking. The off-plan property bought for 900,000 yuan a few years ago was appraised at 700,000 yuan when it was handed over this year. The bank only loaned 560,000 yuan. To hand over the off-plan property, the buyer needs to pay a ransom of 160,000 yuan.The calculation formula for the balance of the off-the-plan property, that is, the down payment ransom for the off-the-plan property: purchase price900,000 - loan amount 560,000 - deposit for off-plan property 180,000 = 160,000.If the buyer cannot come up with the ransom of 160,000 yuan for the down payment when the pre-construction property is handed over, the transaction cannot be completed. Construction costs have risen sharply since 2018 and are still worsening as construction loan interest rates have doubled. The price of new and uncompleted houses remains high and is seriously out of line with the market transaction price of second-hand houses, so there is a situation where a ransom is required to save the down payment. This situation will continue to exist for a long time in the next few years.
02 Make good use of loan policies
Borrowers with floating interest rates can switch to fixed interest rates for free and without penalty, provided that the remaining time of the floating interest rate contract is shorter than the fixed interest rate contract period.For example, a 5-year floating rate contract with 2.5 years left to expire can be converted to a fixed rate contract with a contract period of more than 3 years for free.
Last year, when a loan expired, I chose a floating interest rate with a five-year contract. This year, I switched to a five-year fixed interest rate with no penalty and the interest rate was successfully reduced by 2%.
Borrowers with floating interest rates will suffer different hardships depending on the bank they choose. Some banks, such as BNS and NBC, saw their monthly payments rise as soon as their floating interest rates rose. They suffered terribly during the interest rate hikes in the past two years. Such borrowers can check the remaining time of the original contract and the current fixed interest rate of the original bank. If they can reduce the monthly payment by switching to a fixed interest rate, it will be a very advantageous choice. Because we still don’t know the timetable and extent of the Bank of Canada’s interest rate cut. If the interest rate can be reduced by 1% immediately, it will be equivalent to the central bank cutting interest rates four times, each time by 0.25%, and immediately alleviate the monthly supply pressure. Other banks, such as TD and BMO, allow "negative amortization", that is, if the interest rate increases but the monthly payment remains unchanged, the portion of the interest payable that exceeds the monthly payment is automatically added back to the principal. Such a loan, if converted to a fixed-rate loan in order to lower the interest rate, may increase the monthly payment, so it is not an immediately advantageous choice. For example, if the current monthly payment is 1,000 yuan and it is in a negative amortization state, once it is changed to a fixed interest rate, the monthly payment needs to be reset and may become 1,800 yuan. Although this situation saves interest expenses, the monthly payment is irreversibly increased. It is impossible to reduce the monthly payment to 1,000 yuan. If the borrower has floating-rate loans at BNS and BMO, he or she may consider converting BNS's floating-rate loan to a fixed-rate loan and leaving BMO's loan unchanged until the central bank cuts interest rates.
There are three factors to consider whether to use bank policies to convert floating to fixed, and these three factors are prioritized. First, if the monthly payment increases after switching to a fixed interest rate, it is not recommended to convert from floating to fixed; second, if the original floating interest rate is higher, for example, P minus 0.4%, the current interest rate is 6.8%, and the monthly payment does not increase after switching to a fixed interest rate, the interest rate will immediately drop by more than 1%, and the monthly payment will It will drop immediately, and it is recommended to consider switching to a fixed interest rate; third, although the floating interest rate is very good, for example, P minus 1%, the current interest rate is 6.2%, but there is a HELOC on this loan, and there is an available limit. The monthly payment will not increase after switching to a fixed interest rate, so it is recommended to consider switching to a fixed interest rate.
03 Make good use of the HELOC line of credit for investment properties
A HELOC, a line of credit backed by your home equity, is the best tool for debt management. HELOCs for owner-occupied homes are usually for emergency purposes and are not recommended for debt adjustment. Therefore, the usage of HELOC mentioned below refers specifically to the HELOC for investment properties, not the HELOC for owner-occupied properties.
The existing mortgage loan for property A expires in March this year, and the original bank renewal interest rate is around 5.5%. Because it is a renewal, many banks do not allow the repayment period to be adjusted, and can only reset the monthly payment according to the remaining time and the current interest rate. For example, the current loan balance of property A is 500,000 yuan, the initial repayment period is 30 years, the original 3-year contract is about to expire at this time, the remaining amortization period is 27 years, the renewal interest rate is 5.5%, and the monthly payment will increase from 1,900 yuan to 2,946 yuan. At this time, if property B is an investment property and has an available credit limit of RMB 100,000, the current interest rate of the bank where the loan for property B is located is also 5.5%. At the same time, the bank where the loan for property B is located allows the withdrawal of RMB 100,000 to be converted into an installation loan with a maximum repayment period of 30 years. Then, withdrawing 100,000 yuan from the credit line of House B to accelerate the repayment of the loan of House A can ultimately reduce the overall monthly payment.
If there is an uncompleted property to be delivered in 2024, and there is still a loan for the owner-occupied house, and there is an available credit line HELOC for the investment property, if you have a certain amount of cash on hand, you can use cash to accelerate the repayment of the owner-occupied loan, improve your borrowing capacity, and use the available funds in the HELOC for the investment property to hand over the uncompleted property when the uncompleted property is handed over.
If different banks have different interest rates, and the bank with a HELOC line for investment property has a lower interest rate, you can withdraw money to accelerate the repayment of other loans with higher interest rates, thereby reducing the overall monthly payment and saving interest expenses.
04 Combination boxing
It takes a thousand days to raise an army, but it takes a short time to use it. Now is the time to use your financial intelligence and proactively reduce monthly payments and interest expenses. The long-term accumulation of debt management experience and long-term cash reserves to avoid debt crises and liquidity crises have come into play. This is the moment when Canadian homeowners have the heaviest debt burden, and many families are eagerly waiting for the central bank to cut interest rates. In addition to passively waiting for interest rate cuts, we can now start to proactively help ourselves. From August to November last year, fixed interest rates were above 7%. Households whose loans were due found it difficult to afford such high interest rates, and household balance sheets were seriously damaged. The reason is that the stress test interest rate for previously approved loans was around 5.25%, that is, 5.25% is the upper limit of household mortgage affordability. If the renewal interest rate is higher than 5.25%, borrowers will find it unaffordable. Since this year, the 4- to 5-year fixed interest rates of many banks have dropped to around 5.5%, which is relatively close to the stress test rate. Therefore, by proactively combining the cash situation on hand, mortgage policy, and possible withdrawals from the investment housing credit line HELOC, you can quickly and effectively repair the household balance sheet.
I met a former client at a recent event who told me that there had been some financial changes in her family and wanted my help in revisiting her overall household debt. After the activity, she made a table of her family’s debt situation and sent it to me. After our discussion, I suggested that she use cash to continue to accelerate the repayment of the home loan, regardless of the interest rate of the loan, and then use the available investment housing credit line HELOC to accelerate the repayment of loans on other properties with high interest rates. Find out the investment housing loans due this year, prepare documents to apply for refinancing, stretch the monthly payment back to 30 years, and withdraw the property rights for financial asset investment to supplement cash reserves. It is best to use combination boxing under the guidance of professionals, taking into account current resources and future plans.
Conclusion
Debt management is a lifelong practice for real estate investors. After the outbreak, the period of ultra-low interest rates is the best time to build a position. After interest rates are raised, balance sheets are damaged and interest rates remain high. This is also a time when debt management skills are put to the test. Thunder, rain, and dew are all gifts from God. Real estate investors need to face an all-weather investment environment, but it is not recommended to just passively rely on God to make a living. In January 2024, Canada's inflation rate dropped to 2.9%, and the circle of friends cheered, celebrating that the interest rate cut was just around the corner. But everyone should not forget that last year, in June 2023, the inflation rate dropped to 2.8%, and then reversed. Readers are advised to actively manage their debt rather than just wait and see. The three most important methods of active debt management mentioned above are to avoid reducing real estate positions, combine financial assets and real estate, and combine mortgage policies and mortgage tools to create a beautiful combination and proactively repair the balance sheet. This is a minimalist case set. I have come up with more debt management options over the past six years than can be found in this article. I have recently been working with the landlord.com AI team to train AI intelligent robot assistants. I asked my AI assistant in the AI community how to choose a mortgage interest rate. The AI assistant summarized the essence of my previous articles in a few seconds. AI technology brings us closer to knowledge. A community formed with AI robots as the core will combine people's local experience and global knowledge searched by AI, greatly improving the efficiency and accuracy of information search. The AI community can, after the AI robot gives the answer instantly, the moderators of the local community will give evaluation and judgment. If the answer given by the AI is incorrect or incomplete, the moderators will correct and supplement it. The AI community with me as the moderator will be launched within half a year, and then we can join hands to enter the new world brought to us by AI.