Historical article note: This article was originally published on 2018-01-07. Rates, policies, home prices, statistics, product names and qualification standards reflect the environment at that time and may have changed. This archive is for historical record and general education only. It is not mortgage approval, investment, legal or tax advice.
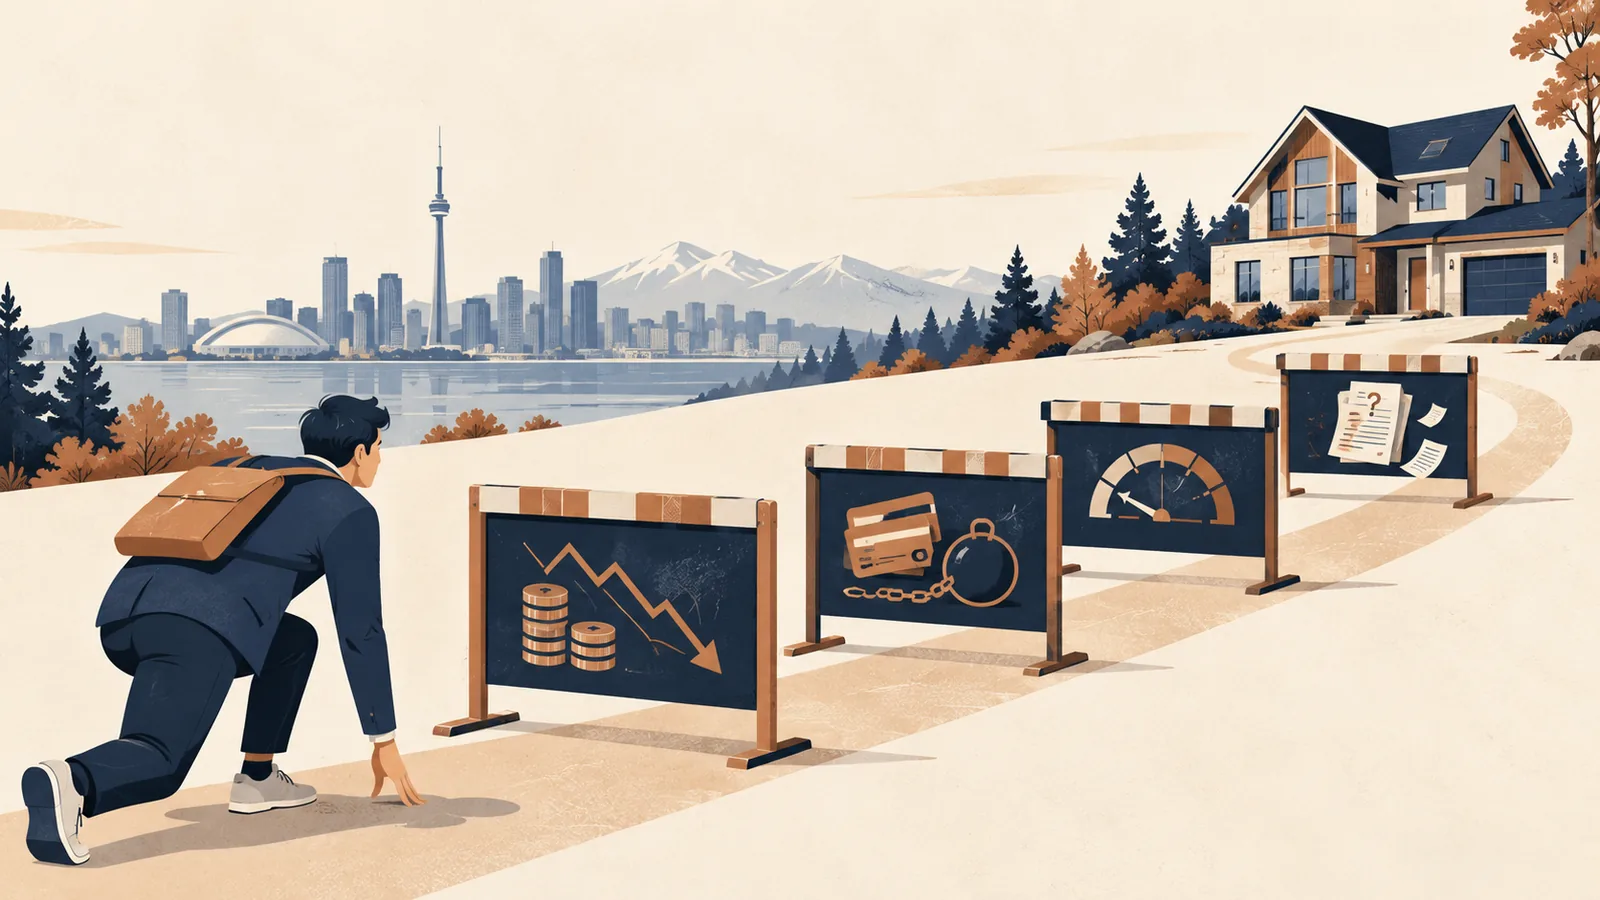
The mortgage loan application process is a comprehensive examination by the bank of the applicant's financial status and credit status. Only if the applicant passes the examination can the loan be approved. Regardless of whether the purpose of buying a house is to live in it or rent it out, the most anxious and difficult step in this real estate transaction is applying for a mortgage loan. There is no use hiding a disease and avoiding medical treatment, unless you buy a house with cash. I have found in my many years of clinical practice that loan applicants instinctively delay applying for a loan until the very end, when they have to. When applying for a mortgage loan, it will be easier to face it, but harder to avoid it. Along the mortgage application process, what killers are waiting for you on the road?
Zero Zero Monster Killer is income. As mentioned in the previous article The Essence of a Mortgage, the secret to getting approved for a mortgage is income, income, income. Some friends don’t understand. They have deposits, stocks, bonds and other monetary assets, and even a large amount of real estate equity. Why does the bank still need to look at income before approving a mortgage? The reason is: you are applying for a loan from a bank, and the bank looks at your repayment ability, not from a pawn shop. The bank does not accept any assets other than the subject property as collateral. There are many types of income that banks can accept to support mortgage applications, including salary income, bonus income, commission income, temporary work income, interest, dividends, rent, etc., as long as it can be proven. The income that banks do not accept is mainly capital gains. Capital gains are Gain, not income, and they do not accept any benefits such as unemployment insurance benefits. Self-employment income, contract labor income, temporary labor income, overtime or bonus income, interest and dividends and other unstable income need to prove continuity and verifiability, so proof of similar income in the past two consecutive years is required. For salary income from employment, only look at the current pay stub to confirm the income level of the current year, and look at the T4 from the previous year or the current employer letter to prove continuity and verifiability. It doesn't matter if you switch to a new employer before buying a house, but it doesn't matter if you change the nature of your employment. For example, if you change from employed to self-employed, banks will look at the continuity and stability of self-employment income for two consecutive years. After the change, it was easy to get a loan, but after the change, you can't borrow a penny. The most serious mistake often made by borrowers is that the self-employment income tax returns are not consecutive. The income in 2015 is reported on line 135 of T1, and the 2016 annual report is reported on line 139. If the two years are averaged, the income is zero. Different banks have the biggest differences in the determination of rental income. Some banks use 50% of the rental income to support loans, and some use 80-90%. The same bank uses 50% of the rental income for investment properties on different occasions, and some use 90%... Applicants need to constantly understand the latest policies of each bank. An investment enthusiast who owns 10 investment houses spent 13 minutes in a 25-minute audio interview talking about how to obtain a mortgage; a Shanghai real estate god said when talking about real estate investment: 80% of the time is spent looking for funds, 15% of the time is spent looking at properties, and 5% of the time is spent on transactions. To buy multiple investment properties, this is how investors actually arrange their time. Income is the most important factor in a mortgage application, because some categories of income depend on the average of two consecutive years. Therefore, it is not too early for friends who are planning to buy a house to prepare to apply for a loan two years in advance. Thinking about it, people who clearly know that they have no income and only start applying for loans after signing a house purchase contract are bound to be intercepted. I often see people posting stories on forums about being framed by "bad" loan brokers. These should be cases of gangsters taking advantage of gangsters. It is obvious that the party who suffered the loss is just an accidental venting of evil fire. With no income and still applying for a loan, it is too accidental not to be robbed. It can’t be fake, and it can’t be fake. There is income, but the loan officer is a novice and may fail, but just change the bank and apply again. Only when you have income can you have a mortgage.
Killer No. 002 is personal debt. Robert Kiyosaki repeatedly emphasizes a truth in the "Rich Dad" series: "House" is a debt, not an asset. The "house" mentioned here specifically refers to the owner's residence. Personal debts are divided into two categories: good debts and bad debts. Among them, debts that are shouldered by oneself are bad debts, and debts that are shouldered by others are good debts. The best-selling book series "Rich Dad" is because the author popularized the bank's view to the public: when banks approve applicants for loans, they distinguish between good debt and bad debt. The upper limit of the loan that an individual's income can support is restricted by the monthly payment of bad debt, and good debt can even help borrowers get a larger loan amount. This is the most difficult mortgage mystery for ordinary consumers to understand. I have heard some people question: Why do "others" have similar incomes to me, but they took out loans to buy 5 or 6 houses, while I have a hard time changing houses? Did the "others" falsify their income documents? The maximum amount of a single mortgage loan is directly related to income; the total amount of multiple mortgage loans is related to the two factors of income + good debt. Bad debts include: monthly home loan payments, monthly car loan payments, monthly student loan payments, and 3% of credit card purchases; good debts mainly refer to mortgage loans for investment properties, because there are tenants helping to repay the loans, so they are good debts. For a borrower who has paid off all bad debts, the cumulative amount of investment housing loans can reach 70 times the annual income, and the amount of each loan will not exceed 5.5 times the annual income. The source of 70 times is this. The loan amount for each investment house is 5 times the income. If you buy 16 units in total, the cumulative loan amount is 80 times the income. After removing some friction costs, it is possible to reach 70 times. Every 100 yuan of monthly payment for bad debt reduces the borrowing capacity by 25,000 yuan. This simple and crude data needs to be kept in mind. If you want to apply for multiple mortgage loans, you need to reduce bad debts.
The applicant who can escape the clutches of Ling Ling Yao and 002 will be easy to deal with several other killers. The fatal killers during mortgage application are actually income and bad debt. No other killer would kill anyone.
Killer No. 003 is the down payment. Mortgage is the leverage provided by the bank. To leverage real estate, a fulcrum is needed, and this fulcrum is the down payment. To buy a home worth RMB 500,000, the minimum down payment is RMB 25,000. To buy a home worth RMB 1 million, the minimum down payment is RMB 75,000. When buying a property worth RMB 1 million or more, whether to live in or rent out, the minimum down payment ratio is 20%. As long as it is for investment purposes, the minimum down payment ratio is 20%. The new B20 promulgated and implemented by the banking regulatory authorities mentioned two contents in the press release: 1. Increase the interest rate of the stress test; 2. Prohibit superimposed loans, that is, the loan ratio for the same property cannot exceed 80%, and the total loan amount of different financial institutions to the target property is strictly prohibited from exceeding 80% of the house price. Therefore, the bank will conduct a strict investigation on the source of the down payment, and the source of large-amount entries into the account before buying a house needs to be explained. The funds from refinancing an existing property can be reasonably and legally used as a down payment for your next home.
Killer No. 004 is credit history. Whether you have repayment habits and whether you have been able to borrow and repay the money you borrowed before are all written on your credit report. Before making an offer to buy a house, you must know what your credit record is. Even if you have never defaulted on a debt, other people's carelessness may make your record worse, so you must check it.
Killer No. 005 is whether the property meets the bank’s requirements. For example, the living area is too small, marijuana houses, group rental houses, illegal construction, does not meet the zoning requirements, apartment buildings with hotels, and second-time transfer of off-the-plan properties, etc. are all properties that banks refuse to loan. Buyers should consult a real estate agent who is familiar with each bank's policies.
Many people fail to realize their plans to buy a house and fail in getting a mortgage because they do not understand the nature of a mortgage, the way banks determine income, and the different attitudes of banks towards good debt and bad debt. Friends who are encouraged to invest in real estate and prepare to buy their own home should do their homework. It is best to have a pre-approval for a mortgage loan in hand to avoid the painful experience of finding a loan and hitting a wall after making an offer. Having a sword in your heart but no sword in your hand is empty talk; having a sword in your heart but having a sword in your hand is a waste; having a sword in your heart and a sword in your hand means you are not afraid of killers on the loan road.