The Canadian real estate market has been very lively in the past half month. First, bank mortgage fixed interest rates skyrocketed within a week, and the five-year fixed interest rate surged to over 3.8%, exceeding the highest point in 2018. Then, Ontario suddenly once again tightened the spell on non-residents buying houses. At the same time, the central bank's sharp sword that may desperately raise interest rates has been hanging in the air. The market temperature in Ontario has changed dramatically. Homeowners who were full of hope for a high price found that buyers were beginning to hesitate, contrary to the pattern of generous and hasty home purchases last month. Buyers and sellers began to become stubborn. One party refused to lower the price, and the other party would never waste money. The result of the tug-of-war may be that the newly recovered listed inventory falls again until a new supply and demand equilibrium point is reached. I estimate this tug of war will last 3-6 months.
What is the de facto reason for “buying a house”? Is it for self-occupation for "rigorous needs"? Or for investment? Or both? Is whether or not to buy a house determined by proximate causes or by factual reasons? People who have thought clearly about the actual reasons for buying a house seldom dwell on the proximate reasons. This is what my friends in the financial business group inspired me. There was a lot of hype outside the group, and the people in the group could only make fun of the quarrelsome people. The real reason for buying a house is investment, not housing. You don’t need to buy a house to live, just rent. Someone once asked me to help with a loan. They asked for a loan of 800,000 yuan with an annual income of 100,000 yuan. They said that they bought a house because they needed it. I cannot accept this reason at all. Buying a house is never a necessity, only renting a house is. People who say that housing prices are too outrageous are not saying that they have no place to live, but that they have been priced out by the market and cannot participate in real estate investment. The fact that housing prices continue to rise is due to excessive currency supply, not limited land resources. Housing prices are mainly a monetary phenomenon. As long as the economy develops, currency increment must be greater than the demand for GDP growth. Otherwise, deflation will occur. All the additional currency cannot be accurately released into the real economy. Some of it must go into real estate, because GDP growth is driven by industrialization and urbanization. When the currency is moderately over-issued, house prices rise steadily; when the currency is excessively over-issued, house prices rise rapidly. We ordinary people can detect this situation with the naked eye. Those who turn a blind eye are superhuman and detached from reality.
01 Long Long time ago Houses are for living in
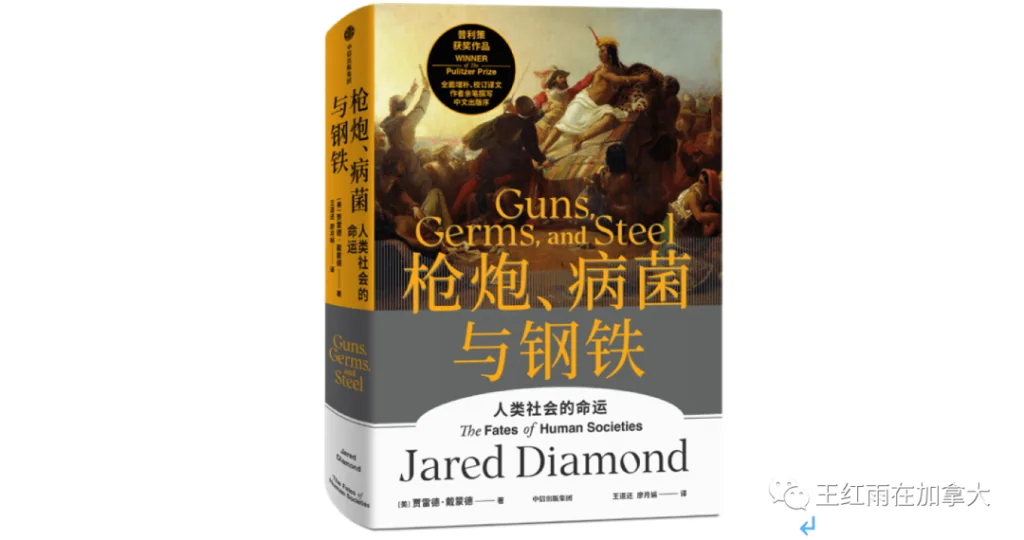
Jared Diamond believes that humans are actually the "third kind of chimpanzee." Compared with the other two close relatives of chimpanzees, humans have too thin skin and too little hair to live in trees or caves. They are too scratchy. Feng Lun gave a definition to house: man-made, the most valuable fixed space. For individuals, the "most value" here refers to the safety, spaciousness and warmth of housing; for businesses, it is the commercial value applicable to social activities. "Fixed space" is the most critical keyword, because settlement is so important to humans. Jared Diamond quoted a true historical story in detail in his other book "Guns, Germs, and Steel". On November 16, 1532, in Cajamarca on the Peruvian plateau, the Inca Emperor Atahualpa met the Spanish adventurer leader Pizarro. The 168 troops led by Pizarro captured Emperor Atahualpa alive with 80,000 infantry. In his book, Diamond copied the historical records of that year, and also conducted a profound analysis: the Spaniards had already adopted a settled lifestyle at that time, domesticating animals as livestock, and plants were also domesticated into crops, eliminating the need for hunting and gathering. Cooperation resulted in a surplus, supporting many people who were engaged in science, smelting, etc. but not farming. So these settled humans brought guns, germs and steel with them into the Inca country, which had not even seen horses or swords, and conquered the Incas in one fell swoop, who were still living by hunting and gathering. This heroic deed was not only recorded in writing, but also widely disseminated. It was the most popular event in Europe at that time, attracting countless adventurers to imitate it. The adventures of the Age of Discovery have since become higher and higher, forming a crushing conquest of the nomadic people by the settled people. Today, settlement has been set as a standard feature of human civilization, and travel and hunting are just entertainment and life embellishments.
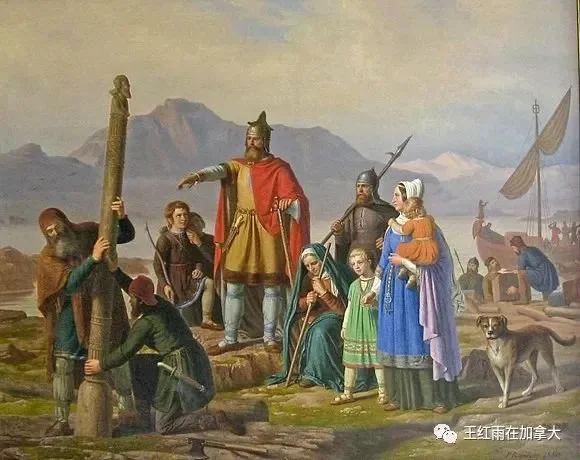
From the beginning of settlement, planting and breeding, humans have gradually solved the problem of food shortage, and through conquest, they have expanded their settled lifestyle to the whole world. Settling down means needing a fixed man-made space. After the social division of labor became refined, man-made houses were specially built and then sold to people who didn’t know how to build their own houses. Hence the real estate industry. After houses become commodities, the range of housing choices becomes wider. At the same time, since transactions require currency, housing prices are also affected by the money supply.
Not every country in the world has commercialized real estate. For example, in Singapore and Germany, the state dominates housing allocation, not the market. The real estate market in North America is almost purely market-oriented. However, in recent years, the left-leaning political atmosphere is trying to decommodify real estate. Some groups continue to encourage the government to welfare housing. The reason is that rising housing prices have priced out many families who have lost out in market competition. The proportion of demonetized government welfare housing in Canada is very low, about 1%, and the vast majority of people cannot obtain welfare housing. If you want to apply for welfare housing, you need to be older, weaker, miserable, unlucky, and the winner will get it; this is in competition with the market, stronger, faster, and determined. It does not seem to be easy, because the total number of welfare housing is too small, and the probability of winning and getting welfare housing is too low. The first immigrants to land in North America were eligible to receive a piece of land as soon as they landed. However, new immigrants in the past 100 years can only buy built properties from old immigrants. Canada has had the highest proportion of new immigrants among G7 countries in the past 10 years, and the total number of new immigrants in 2021 exceeded the United States for the first time. New immigrants have discovered that Canada’s second-hand housing market is completely commercialized, with no purchase or loan restrictions or household registration discrimination. Buying early has a very strong timing advantage. The longer you wait, the more new immigrants there are, the fiercer the competition, and the higher the housing prices. In 2007, when I was still working at Bank of China's New York branch, I took advantage of a business trip to buy my first home in Toronto. I didn't come here to live there permanently until the end of 2008. When I bought the home in 2007, the mortgage interest rate was 4.5%. But my wife and I both knew very well that since Canadian real estate is market-oriented and commercialized, and new immigrants will continue to pour in, buying early is the only option. In 2010, our family bought our first investment house, and this second house was used for investment. From the perspective of human history, houses were originally used for living. From the perspective of a new immigrant,The initial purpose of buying a house was to live in it. With the development of time and my understanding of the real estate marketization, I gradually began to explore the path of investing in real estate. When you buy an investment property, you don't live in it yourself. Instead, you obtain the right to collect rent by transferring the right to use it, provide a place for tenants to live, and at the same time collect rent as a landlord.
After living for a long time and drinking too much water in Canada, I realized that Canadian houses can be invested. The cognitive lag has hindered many new immigrants from investing in real estate. Even today, some people stubbornly believe that buying investment houses is a bad behavior that squeezes out other people's rights to buy their own homes. When investing, you should invest in industry, not real estate. Long time ago, houses were only for living in, but now, in Canada, houses can be invested, and real estate investors are providing rental properties for tenants. For landlords, investing in real estate is a small business that does not require all resources to be invested. While investing in real estate, you can take care of your normal work.
02 Don’t chase a horse, use the time you spend chasing the horse to plant grass.
Some people accuse real estate investors of turning their backs on reality, investing precious resources in idling capital, corrupting customs, getting something for nothing, pushing up housing prices, and harming the next generation. They believe that they should invest in the real economy, industry, and start-up enterprises. Only in this way can it be considered an investment, and such investment is glorious. I dismiss this criticism. The prerequisite for participating in real estate investment is to obtain a bank loan. To obtain a loan, you must contribute to the real economy, have income, and pay enough taxes. Real estate investors are leaders in the competition in the real economy, otherwise they would not be able to invest in real estate in such a high housing price environment.
Anyone buying a house is an investment behavior. All countries never include housing prices when calculating the consumer price index, only rent and mortgage interest, because "buying a house" is included in the national economic statistics of any country as an investment behavior, not consumption. Buying a house to live in is an investment, and buying a house to rent to others is also an investment. There is no shame in buying a house and renting it to others. I don't see anything noble about renting a landlord's house and investing my savings in a startup.
In Canada, it is not easy to afford a rental house. Real estate investors need to immerse themselves in the real economy, find a place in the highly competitive workplace, stick to their jobs without receiving benefits during the outbreak of the epidemic, and at the same time, be a proactive tax payer in Canada who contributes to society, otherwise banks will not grant loans. Some people who cannot find a place in Canada continue to sarcastically imply that those who can still get loans despite such high housing prices are doing so by falsifying their income documents. People who think this way can only show that they are out of touch with hard-working middle-class families. Falsifying income documents is a felony, and the RCMP at the federal level handle such criminal cases, not the police at the provincial level. There must be some people who dare to test the law, but it is unlikely to be the majority. The multi-suite real estate investors I know are all the most honest and hard-working middle-class families. They are outstanding representatives of being involved in the real economy. There is nothing wrong with investing their savings in real estate. 96% of the price paid by buyers of second-hand houses goes to the sellers and 4% to real estate agents. The sale of second-hand houses has never harmed the real economy and completely follows the law of conservation of energy. Buyers of second-hand houses feel that they have been left out of pocket because they finally participated in real estate investment, but they just bought too late. But don’t forget that there are 300,000 to 400,000 new immigrants on the way every year, and it is never too late to buy. But for a family that has already landed in Canada, the sooner you buy a house, the better.
Many families lament when looking at housing prices, lamenting that the rise in housing prices has exceeded their affordability and that they have been priced out. I think it’s better to work deeply than to lament. A person's social value depends on the irreplaceability of his or her work, which requires new immigrants to find their comparative competitive advantages as soon as possible and become useful people to Canadian society. An important sign of a mature society is that any opportunism has corresponding consequences waiting for you. People who have been receiving epidemic relief for a long time, people who work in cash and do not file taxes, people who are addicted to pyramid schemes, and people who rely on savings to live, it is now difficult to apply for loans. This is a cause and effect. Finding one's place in the real economy, working deeply, creating value, and reinvesting in real estate are the shortcuts for new immigrants to invest in real estate. In addition, all other fancy attempts to obtain real estate will ultimately fail, even if they are lucky enough to succeed a few times.
After Tu Youyou won the Nobel Prize, she said: Don’t chase a horse. Use the time you spend chasing the horse to plant grass. When the grass grows, the horse will naturally come back to eat grass. Those who spend money and time to attend real estate investment classes and mortgage classes are chasing house prices; those middle-class families who work conscientiously and file taxes honestly are quietly planting grass. It is becoming increasingly difficult for new immigrants who are like duckweeds to get loans. They even wonder if there is a problem with Canada's system. In fact, the problem lies with themselves. In essence, Canada's social and economic system is advanced and mature. It respects the work ethic of "no work, no food". Those who do not work and do not pay taxes will not be able to cross the threshold for loans.
03 The elephant in the room is currency
When it comes to buying a house, one topic that cannot be avoided is housing prices. I noticed that many people looked at the changes in house prices in the rearview mirror and diligently analyzed the transaction records of the previous month. In fact, this kind of analysis is the same as the approach of stock commentators. They treat transaction data as post-truth, perform cosmetic or rationalization, and use imagination to explain why which stocks rise or fall, and why house prices in which areas rise or fall, in order to find the trend of changes in stock prices or house prices. These analysis methods themselves are trying to find fish from a tree, so no correct answer can be found at all.
The epidemic has given us an opportunity to analyze housing prices in the laboratory. After the lockdown, working from home, rising unemployment, interest rate cuts, and no inflow of new immigrants and non-residents, we can examine under unprecedented control conditions what are the root causes of changes in housing prices. The golden rule of housing prices, location The elephant in the room is currency.
Sellers and buyers eager to know where home prices will go this year have been keeping an eye on the Bank of Canada's words and deeds, trying to get a glimpse of the direction of monetary policy. The Bank of Canada has been saying tough things, threatening to raise interest rates aggressively and continuously, regardless of the debt problem and only focusing on inflation. There is a reason for the central bank's harsh words. On March 2, the central bank only raised interest rates by 0.25%. Investors thought it was using French fries as a door bolt to ward off gangsters, so inflation expectations are very high. Inflation and inflation expectations are two different things. If inflation expectations rise, the face value of bonds will plummet, causing bond yields to skyrocket. This is what I said at the beginning of the article. As bond yields surged by 20% in one week, mortgage fixed interest rates skyrocketed. When the central bank saw the 5-year government bond yield reaching 2.5% on March 25, it immediately made harsh words to raise interest rates sharply. Spelling is a commonly used "expectation management" method by central banks in the hope that the market will reduce expectations for inflation and bring down bond yields. Although shouting may be effective as the lowest-cost method, it is extremely risky. If the market does not buy it and continues to sell bonds to suppress bond prices and push up bond yields, the central bank must fulfill the promises made when talking big, otherwise it will lose its credibility. If we really raise interest rates sharply, the economy will inevitably fall into recession. This is an undoubted result. Inflation may not necessarily come down, but the economy will definitely decline. The more high-profile the central bank speaks, the higher the stakes, and all borrowers are chips, including the federal government. In fact, raising interest rates cannot reduce inflation. It will only cause economic recession. Only when the economy declines will inflation come down. Taking economic recession as the price of reducing inflation is not worth the gain. Throwing the bath water out will throw the baby out. The faster interest rates are raised, the sooner the recession will come and the sooner interest rates will be cut.
As for whether the Bank of Canada will shrink its balance sheet, the central bank has not mentioned this sensitive topic for a long time. The investment community generally believes that the probability of shrinking the balance sheet is very small. Shrinking the balance sheet means taking back the cash currently in circulation. The direct result is deflation, that is, money shortage. The result is debt appreciation and price decline. When borrowing money, 100 Canadian dollars can buy 20 kilograms of pork, and when repaying the money, 100 Canadian dollars can buy 50 kilograms of pork. The consequences of shrinking the balance sheet are unbearable for the federal government. In addition, deflationary factors already exist. The suspension of epidemic subsidies, rising oil prices, and rising interest rates are all weakening effective demand. If the balance sheet begins to shrink, it will lead to real deflation and further reduce demand. When mankind used gold as the anchor to issue currency, it suffered from a "money shortage". Finally, in 1971, the gold anchor was cut off and freedom of money printing was realized. Therefore, deflation is rarely seen in the world.
Regarding the interpretation of monetary policy, I recommend everyone to watch a video of a financial post on YouTube, why the bank of Canada is now “talking tough” on inflation. Industry insiders believe that neither Canada nor the United States will raise interest rates by more than 2% this year, and bond yields will hover around 2.5% instead of creating a new ceiling. It is unlikely that the balance sheet will be reduced.
The golden rule of capitalism is money talks. During this epidemic, each of us has received a re-education of this sentence. Regarding the issue of housing prices, except for low interest rates and currency depletion, all economic factors point to a decline in housing prices, but housing prices have actually skyrocketed. Currency has single-handedly pushed up housing prices. Dalio explained the problem of the money multiplier in the video How the Economic Machine Runs. After the central bank releases high-energy base money, commercial banks will amplify currency issuance through credit. The money multiplier is the reciprocal of the deposit reserve. Canada's deposit reserve ratio is 2.5%, and the amplifier effect is very strong. Only the central bank can legally print money, and ordinary people cannot. However, commercial banks can print money for real estate investors by adding mortgages to real estate. This is a kind of currency that is issued to real estate investors, so the currency in circulation is still increasing as housing prices rise. Banks are money printing machines for real estate investors, and this game is still in progress. The base currency released by the central bank has been hard to recover. On this basis, commercial banks can issue large-scale targeted banknotes to real estate investors through additional mortgages. This is what we are seeing now. The net assets of families investing in real estate have skyrocketed. People who unrealistically hope that house prices will fall cheer when they see someone expecting a 15% drop in house prices. This is a disrespect for the golden rule of capitalism.
Some economists predict that by the end of this year, the overnight interest rates of the central banks of Canada and the United States will rise to 2.75%. The result of rapid interest rate hikes is economic recession, but prices do not necessarily fall. Inflationary recession is actually the bottom line of monetary policy. "Bottom line thinking" means that in the face of major challenges, don't think about development, just don't collapse. Canada's bottom line thinking is very simple and clear: if recession and inflation occur at the same time, votes are not guaranteed, and losing votes is the bottom line of monetary policy. Once it hits the rocks, the policy will change and start cutting interest rates again, or even start QE again and issue more money.
04 The risk of buying a house can only be summed up in three words
In a recent video debate, the opponent’s fellow debater talked about the risks of additional mortgages. Many people in the comment area asked me why I didn’t talk about the risks. I replied: "The risk of additional mortgage is assessed by the bank, and no one else needs to say anything." The essence of home purchase loans and loan mortgages is that the bank evaluates how much money it can lend you. Not just anyone who wants to leverage can do so. Residents who have no income and do not pay taxes will find it difficult to leverage. There are steel scales in the bank, and the weights are income and repayment ability. If the bank approves you to increase the loan amount to 80% of the current house price, it means that the applicant has passed the stress test with an interest rate of 5.25%. If someone does not believe the bank's assessment, you can also make your own assessment. See my YouTube video "We are forced to invest in order to balance our lifetime income", risk management chapter: Risk = the possibility of loss X. Risk management methods include transfer, reduction, avoidance, and retention. There is no such thing as a risk-free win, and the ability to bear risks depends on the depth of roots in Canadian society. Even if a family like duckweed passes the self-assessment, it will not pass the bank's risk assessment.
There are two assumptions facing home buyers: 1. If the house price drops after buying it, I will lose money if I buy it now; 2. If I don’t buy it, if the house price rises, I may not be able to afford it in the future. People who buy a house based on Assumption 1 basically cannot buy a house. Only families who buy a house based on Assumption 2 may be able to buy a house before housing prices are about to exceed their affordability. Families that have harbored hypothesis 1 for many years are either looking forward to falling house prices or have been priced out. The biggest risk in buying a house is three words: wait.
Having been in the mortgage business for more than 12 years, I have met all kinds of wait-and-see experts.
"You won't be responsible for the other bank's fine when you transfer a bank to add a mortgage, oh, I'll wait a little longer";
"My loan is due in half a year. The penalty for extra mortgage is too high now. I'll just wait."
"House prices are too high now. I can get a salary increase of 5,000 in the second half of the year. I'll wait and see if house prices can come down and if I can borrow more."
"I need to mortgage three more houses to get the down payment for house replacement. The fines are too high. I'll just wait."
The experts soon discovered that while they were waiting, all the low-hanging fruits had been picked, and that to reach the apples they needed to climb a higher ladder. Since the outbreak of the epidemic, the average house price in Canada has increased by 54%. The low-hanging fruits have been swept away, and the number of people who can afford to buy a house has significantly decreased. However, families who can afford a house have found that they can buy up to 10 rental houses as long as they continue to accelerate the repayment of their home loans and at the same time add mortgages to their existing investment properties. Therefore, we have seen that the transaction volume of the real estate market has not decreased during the epidemic, but has increased.
Every family faces its own constraints when buying a house. Families who work hard to buy a house will try their best to overcome these constraints and will buy even if there are no conditions to create conditions; while those who wait and see find ways to set constraints for themselves, even if the fine is only 500 yuan, it can stop them from moving forward. When interest rates dropped sharply in 2020, bank fines were very high. One of my clients was fined 30,000 yuan when refinancing, but withdrew the down payments of two investment houses, which were all used as down payments to buy two more investment houses that year. The 30,000 yuan fine did not come out of their pockets, but was capitalized into the principal of the new loan. The repayment period is 30 years and the annual cost is 1,000 yuan. In addition, this fine can be used as the financial expense of the investment house to offset the net rental income. Families that can make this kind of decision during the epidemic understand the costs and benefits, and see through the facts behind the proximate causes, otherwise they would not be so decisive. Some people get jealous when they see others making money by investing in real estate. Don’t they know that the financial intelligence and courage behind this cannot be developed in a day?
The biggest and most obvious characteristics of the Waiting people are penny wise, dollar foolish, short-sighted, poor in action, and unrealistically optimistic about uncertainty. Many families with high incomes have this problem. They are only familiar with their own professional fields and have low financial intelligence. The result is that although they have high incomes, they are unable to accumulate wealth.
05 Should certainty come at a premium or a discount?
If there is a down payment, whether to buy a second-hand house or an off-the-plan property, I had a lengthy debate with a fellow debater because he needed three-quarters of the time to explain his point of view. I saw an article a few days ago saying that Wall Street's IPOs have entered an ice age in the past year. The reason is that companies with concepts but no profits are always losing money, and no one is willing to pay for their dreams. Second-hand houses and blue-chip stocks have a common feature: they generate cash flow when bought; the same thing between off-the-plan properties and growth stocks is that they are a dream to buy. If a person says that a second-hand condominium is selling for 700,000 yuan and I can't afford it, I'd better buy a 900,000-yuan off-the-plan condominium, because buying a second-hand condominium requires a down payment of 140,000 yuan immediately, while buying an off-the-plan condominium only requires a downpayment of 180,000 yuan in one and a half years. Do you think this is the normal thinking of an investor? A rational market should give a premium to certainty and a discount to uncertainty. It is difficult to IPO concept stocks in the capital market, which shows that rationality is returning and value investment is returning. It is hoped that Canadian real estate investment will return to rationality and value as soon as possible.
Assuming that the uncompleted property can be settled normally, the investment income from buying a second-hand house is the opportunity cost of buying the uncompleted property. If the opportunity cost is 700,000 and the profit from buying an off-the-plan property is 300,000, then compared to the opportunity cost, the loss is 400,000. When funds are limited, opportunity costs must be considered when deciding what to invest and how to invest.
Why do people prefer investing in real estate rather than investing in startups in Canada? The reason is obvious, the return on investment property is more certain. Everyone sees this certainty, so they chase certainty of investment returns, which also pushes up housing prices. Conservative Party leadership candidate Pierre said in a video that the depreciation of the Canadian dollar caused by additional currency issuance is most obvious in housing prices. On the one hand, houses are the hardest hard assets, and on the other hand, because a large amount of money chases the certainty of investment returns, houses are still those houses before and after the epidemic, but because the Canadian dollar has depreciated the most relative to houses, we have seen skyrocketing house prices.
The price tags of off-the-plan properties are riding the coattails of second-hand houses. Because it is difficult to find a house in the second-hand housing market, sales staff lead speculative buyers to the off-the-plan property market. In addition to the self-interest bias of the sales staff, off-plan sales also attracted speculators who had no borrowing ability but wanted to try their hand in real estate investment, and the two parties hit it off. People who have had their down payments locked into deposit accounts by developers join the sales staff in defending this speculative behavior, so the debate takes longer.
06 The impact of factual causes and proximate causes on real estate investment
People who call buying a house a rigid necessity have ulterior motives, because "buying a house" has never been a rigid necessity, and it is not a rigid necessity in any country. Only renting a house is a rigid necessity. Living decently and safely is a sign of civilization, but this does not mean that a society where everyone can afford a house is a civilized society. Singaporeans do not need to buy a house and can live a civilized life. The actual reason for buying a house is investment as well as living needs.
When to buy a house also depends on the actual reasons, not the proximate reasons. The proximate causes of buying a house in Canada actually have little impact on real estate investment, because when we look back at those proximate causes, they are just market noise. Therefore, when to buy a house, or when to start investing in real estate, still depends on the actual reasons: that is, did you decide to invest in real estate instead of other assets? Can the bank grant you a mortgage loan? For factual reasons, if you want to invest in property, do it sooner rather than later. In the first quarter of 2022, the Canadian government approved 150,000 new immigrants, and 100,000 people have landed. These new immigrants are the same kind as us. They have very thin skin and very little hair. They are not suitable for living in caves and trees. Let the people who wait a little longer hesitate, the new immigrants can't wait to land.
The proximate causes have been analyzed badly by real estate practitioners, so I will briefly talk about them, because sooner or later these proximate causes will become noise.
Ontario's new policy has basically blocked the possibility of non-residents buying houses. Unless they encounter a particularly bad-tempered non-resident, or have already confirmed that they can obtain their new immigrant status, no non-resident will pay the 20% real estate speculation tax first and then wait for the refund after they obtain their new immigrant status. Ontario’s new policies will first have an impact on the most unreliable off-the-plan property sales, secondly have some impact on second-hand condo sales, and finally, and most importantly, will push up rents.
The Bank of Canada's monetary policy has been riding on the back of a tiger and has been unable to change for nearly a year. This aggressive management model of expectations will continue for a period of time. During this period, the forecasts from various gods will not stop, but they are definitely predicting a decline in housing prices. The seller will suffer more, and the buyer will have room to negotiate the price. The specific suggestion is that sellers who are not in a hurry can change their houses to rentals, and buyers should seize the opportunity to breathe in this market. House prices will not fall as the noise shouts, because house prices are deep. As long as house prices fall, the number of listings will decrease. In Canada's second-hand housing market, sellers have always been drivers and buyers are passengers. When the fare is low, the driver takes a rest. Housing prices are stable, and real estate investors’ operations of increasing mortgages and printing money are not affected. Investors can wait for monetary policy to bottom out. The faster interest rates are raised, the faster it will bottom out. Bottoming out means that after the economy falls into recession and inflation, it will kill votes and lead to another interest rate cut and money printing. I believe that the coalition government of the Liberal Party and the NDP will be able to achieve this.
The mortgage policies of commercial banks will not change much. Modifications of certain projects of individual banks have nothing to do with the overall situation. The recent fine-tuning of commercial bank mortgage policies is reflected in two aspects: 1. It has basically completely blocked the back door for new immigrants to obtain mortgage loans without Canadian income, reducing the possibility of new immigrants taking out loans to buy luxury homes as soon as they land; 2. Due to high housing prices, the borrowing ability of middle-class families has been relatively reduced. Banks have developed their own high-net-worth projects to cope with this situation. Families with high deposits will have certain advantages. The stress test interest rate policy is controlled by OSFI. It is currently 5.25%, which is already lower than the 5-year fixed interest rate + 2% pricing model. However, OSFI decides whether to adjust the stress test interest rate. This is unpredictable. The timetable for resetting the stress test interest rate should be June this year.
There is nothing new in the Ontario government’s supply-side reform of housing construction, mainly because it does not provide effective incentives to developers. Most of Ontario's housing construction companies are small and medium-sized enterprises, or even start-up companies, and there are very few large developers. Therefore, long-term and effective incentive mechanisms need to be provided to attract large capital to enter the housing construction field. In addition, Canadian commercial banks are relatively conservative in financing housing construction, especially for start-up developers, and basically do not provide loans. To build houses, start-ups must rely on high-cost financing from non-bank financial institutions. Financing forms such as joint mortgages that have appeared in the past have failed to pass the test of the market. Developers are unreliable and the financing channels behind them are unreliable. As a result, the projects undertaken by new developers are extremely unreliable. The faster they develop, the more unfinished they are. The biggest characteristics of Canada's real estate development industry are insufficient production capacity, too high administrative costs, too long construction cycles, high risks of unfinished projects, and too many start-ups that don't know where to start. These are all caused by the shrinking scale of real estate development in the post-urbanization period. For real estate investors, they should try to stay away from the primary real estate market. If they are unclear about the details, they should not participate in anyone's fund-raising development projects. We are also not encouraged to speculate on off-the-plan properties. Just focus on second-hand housing investment. Supply-side reform is 100 times more difficult than demand-side reform. This is why when it comes to real estate policy adjustments, the government always starts from the demand side to stop the boiling water, instead of raising wages from the supply side. A few shouts from Ford will only affect the outcome of this year's provincial election, but will not change the current situation on the supply side.
Fixed interest rates have skyrocketed, so everyone can choose floating interest rates. Even if floating interest rates will rise as the central bank raises interest rates, it is difficult for central bank interest rates to stay high for a long time. Real estate investors can continue to enjoy long-term low interest rates if they grit their teeth and survive the period of high interest rates.
Conclusion:
Finally, let’s talk about the retreat, about human beings. Many people are deeply worried about the economic recession, but I am not worried about it because I think it is a high probability event. In October 2019, there were obvious signs of recession. It is recommended to read the article "The Causes of Economic Recession and How to Deal with it" that I wrote at that time. Human beings cannot control inflation by raising interest rates, even if Volcker is resurrected. Raising interest rates can only lead to economic recession. If there is a recession, everyone will tighten their wallets, and inflation will disappear. Taming inflation without causing recession requires the use of the deflationary weapon of mass destruction—technological progress. New technologies will improve efficiency, reduce production costs, lower commodity prices, and hedge inflation by creating deflation, so that inflation can be fundamentally tamed. New technologies will create new demand from the supply side and at the same time reduce the cost of existing goods. This is what Steve Jobs said back then, that new technologies can create deflation. The current inflation proves from the negative side that mankind has lacked fundamental technological innovation for a long time. In the competition for existing wealth, there will be no cyclical development, only structural differentiation, and the gap between the rich and the poor is getting wider and wider. If you don't want the poor to rebel, you have to distribute money. The more money you get, the more the currency will depreciate. If the middle class doesn't want to be caught between the rich and the poor, they have to print money themselves and use money from investment properties to beat inflation. I may be pessimistic. I don’t think humans can make any breakthroughs in supply-side technological progress in the short term. Money printing cannot stop, so inflation will become a long-term phenomenon, and interest rates cannot remain high for a long time due to bottom-line thinking. Therefore, high inflation and low interest rates will coexist, no matter how the central bank talks.
"Do what you should do, and don't be affected by proximate causes." This sentence is easy to say, but difficult to do. If you follow your own plan and buy a house now, you may seem very unsociable. Thinking back, after the outbreak of the epidemic in 2020, those who dared to pay a fine of RMB 30,000, take out additional mortgages and take out the down payment to buy two investment houses, aren’t their money-making methods unsociable? Only by having the courage to take risks correctly can you pursue higher risk compensation. Buying early, no matter what happens in the near future, is a sign of a sophisticated real estate investor. Those who are shaken by market shocks are those who cannot figure out the actual causes and proximate causes. The wealth gap between qualified investors and other groups will become wider amid market fluctuations.
The most valuable fixed man-made space in Canada is used for investment and also has the function of living. The reason is that housing prices are a monetary phenomenon. The Liberal Party and the NDP's powerful combination of robbing the rich and helping the poor has determined that until 2025, Canada will have a monetary and fiscal policy model of central bank printing money + government overspending. Middle-class families need to print money by themselves in order to offset the decline in the purchasing power of banknotes caused by the government's currency release.
If a person has no long-term worries, he will have immediate worries; if he cannot see the actual causes clearly, he will be confused by the immediate causes. Proximate causes influence people's judgments and choices in a constantly changing manner. Life is the sum of choices.
Families with multiple investment properties can take advantage of existing bank policies to cash out their existing investment properties and buy more properties. This is a fact. This closed loop has been recognized by the regulatory authorities and is not a management loophole. Peter from OSFI, the banking regulatory authority, confirmed in an interview that this closed-loop phenomenon does exist and that there is no intention to destroy this closed-loop. After the central bank releases the base currency, commercial banks print money specifically for real estate investors. It is understandable to reward these families who have contributed to the real economy. When Rawls defined "justice", he said that justice is moral desert. Sandwiched between the rich and the poor, middle-class families are favored by commercial banks and are morally entitled. The real estate investment of middle-class families in a closed loop is a just investment in the Canadian environment. Canada's political and economic system is very mature and stable, and closed-loop policies have always existed. Chinese people who will not take advantage of this policy, or are not qualified, do not need to be jealous, and just accept the gap in real estate wealth. The property tax, interest and management fees of investment properties can be tax deducted for a long time. Some families will not take advantage of or are not qualified to take advantage of these tax benefits. This is not a problem of the policy itself, but whether there are financial problems, whether they work well and pay taxes. Under Canada's existing loan and tax policies, Canadian houses are used for investment and also have residential functions.
Canada's announcement to open its doors means that the epidemic crisis is over in Canada. Two years ago, I wrote an article suggesting that everyone take advantage of the epidemic crisis to accumulate family wealth. Now the time window for the epidemic crisis has been officially closed. The next crisis is global and Canadian inflation. The principle is the same. We only see families in danger and those who can seize opportunities. After the crisis is over, the wealth gap continues to widen. If we wait any longer, we will miss out on this inflationary crisis again unless we change our past and act immediately.
When Canada drinks too much water, some thoughts and opinions naturally arise. I know that my voice sounds very unsociable, but these are my own observations, as well as my true feelings and thoughts. I use my brain, heart, and logic to code the words for everyone's reference and reference.