For real estate investors, 2022 is a year full of challenges and worthy of serious reflection. In the past year, most people gained far less than their experiences and lessons. They missed too much and gained too little.
Seven consecutive interest rate hikes were the main theme throughout the year, and the market's 180-degree reversal was unforgettable. For most of the year, fear has tied up people's thinking and actions. Many people have been lost in the fog in front of them, forgotten their distant goals, and even deviated from the established route. Only by carefully summarizing experience and lessons can we overcome the current difficulties, establish correct investment concepts, and prepare for the future of real estate investment. Next year, the current high interest rate environment will continue, but smart investors should not make the mistakes of this year again.
Real estate investment is a long-term investment. Looking back at the housing prices 10 years ago, we all feel that they were too cheap. We should have bought more houses at that time. If we can look back today 10 years later, I think many people will say that 2022 will be the most ferocious year for interest rate hikes. Even so, housing prices at that time were only down 20% from the highest point, and housing prices were still 40% higher than before the epidemic. Why didn't we take action at that time? In order to avoid regrets ten years later, we need to carefully review and summarize what we missed and what we learned in 2022. This article will sort out my reflections on 2022, hoping to inspire the majority of real estate investors.
01 Leviathan in modern society
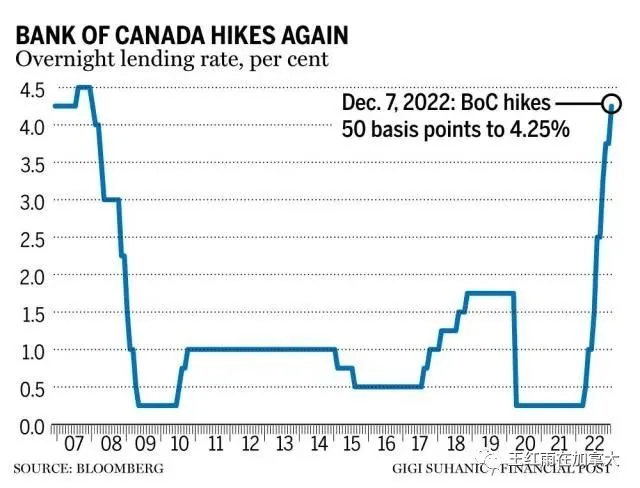
The person who has attracted much attention in Canada this year is not the prime minister, the leader of the opposition party, or the minister of finance, but the governor of the central bank. In 10 months, the central bank has raised interest rates 7 times. The central bank has raised interest rates from 0.25% at the beginning of the year to 4.25% in one fell swoop. It has not yet made it clear that it will no longer raise interest rates. This suffocating rate and magnitude of interest rate hikes has made all Canadians hold their breath, carefully listening and pondering every statement made by the central bank governor. On December 12, the central bank governor’s speech at the Business Council of British Columbia was the last public speech of the year. Governor Tiff McClem’s expression was the most relaxed in a year. Tiff summarized three surprises and three lessons learned before and after the decision to raise interest rates. This speech video deserves our careful study.
Tim has repeatedly mentioned the central bank's models and model failures. This is particularly worthy of reflection by each of us. No historical data and experience can accurately predict the future. Facing the future, we need to remain in awe, as well as have sufficient safety margins and adaptability. At the end of last year, the central bank still did not make the decision to raise interest rates because the model judged that rising oil prices would not lead to long-term large-scale inflation. Therefore, the model judged that inflation was temporary. It was not until the outbreak of the Goose-Bird War on February 14 this year that the conclusions predicted by this model were abandoned because oil prices could not fall back in a short time; supply chain interruptions were also assessed as temporary difficulties by the model. As the world unblocked and resumed production, the situation of demand exceeding supply should have been alleviated. However, a major manufacturing country that is an important link in the supply chain actually delayed unblocking for a year, which was not expected by the model. Tim confirmed that Canada's future supply chain must be able to The central bank itself is powerless to ensure that it is based on friendly and trustworthy partners. It can only suppress strong demand with excessive interest rate hikes and buy time to reorganize the supply chain. Finally, the average harms the central bank's judgment. The demand itself is balanced, but the supply is extremely unbalanced. The manufacturing and service industries have recovered at the same time, resulting in the labor force being unable to satisfy various industries in a balanced manner, resulting in a spiraling upward trend in prices and labor costs. Tim's hindsight-style summary is sincere and consistent with the facts. However, this kind of review cannot relieve the financial pressure and tension of ordinary people. The central bank's misjudgment will bring great pain and uncertainty to ordinary families. It is an abnormal thing in itself for the whole country to stare at the central bank governor. A qualified central bank governor should be a forgotten role, quietly completing his job - maintaining currency stability. What is disappointing is that in Canada, the purchasing power of the Canadian dollar will decline rapidly in 2022, and households with heavy debt burdens will bear the financial and psychological pressure caused by the skyrocketing interest payments during the violent interest rate hikes.
The first reflection that 2022 brings to each of our families is:While families are doing their best for financial security, there is a huge unstable factor that lingers for a long time and has nothing to do with personal efforts. That is the instability of the purchasing power of money and the financial risks to families caused by monetary policy.Macroeconomic policies have little to do with our personal lives when the economy is running smoothly, but when economic policies are artificially interfered with, our lives will be disrupted. It is regarded as a globally recognized and credible economics textbook and was written by Samuelson. Samuelson was a Keynesian who believed that fiscal policy can correct market failures, especially when economic overheating or recession occurs, relying on public spending to balance economic development. It was not until the last edition of his textbook, the nineteenth edition, that he admitted that macroeconomic control methods had developed from fiscal policy to monetary policy. That is, when the government carries out macroeconomic control, the first thing it does is to raise or lower interest rates, and to relax or tighten monetary policy. It is difficult for people who do not carefully study the history of economic development to detect this change. At present, the world is not ruled by the United Nations, but by the central bank governors of various countries. They have the power to raise or lower interest rates, and to relax or tighten monetary policy. The financial security of each of our families is affected by the monetary policy of the country where we live.
The central bank exercises state power to formulate policies and is not subject to public supervision. There are constant voices of opposition to the central bank's policies in the Canadian Parliament, but all dissatisfaction can be resolved by saying "the central bank is independent". This absolute power is the state power described in "Leviathan" published in 1651. Hobbes, the author of "Leviathan", believed that human beings are enemies of each other in the state of nature, and there must be an absolute power, that is, Leviathan, to maintain social order. Distrust in the market economy has led today's capitalism step by step to the point where it relies on power to intervene in the economy. Every country is balancing between market economy and power intervention. In the past 20 years, the dominant position of the market has been continuously eroded by Leviathan. However, the central bank governor is in a decision-making position alone and cannot be smarter than the collective wisdom of the market. In Canada, in 2022, a farce in which Leviathan failed and everyone took the blame was staged right before our eyes.
When you open the official website of the Bank of Canada, the first sentence that comes into view is "We are Canada’s central bank. We work to preserve the value of money by keeping inflation low and stable." I think that the second sentence of these two sentences should not use a period, but a question mark. My personal view is,In the short term, Leviathan has the ability to solve immediate problems, rely on violent interest rate hikes to quell runaway inflation, and slowly lower interest rates. In the long term, the central bank is unable to maintain currency stability, because in the economy, the expenditure of the Ministry of Finance is not restricted by the central bank. Especially in Canada, the behavior of spending money to buy votes and please some voters makes vested interests happy.As a family, we need to find a way to our own financial security in the market, at least to ensure that our labor income does not depreciate. Relying on a Leviathan like the central bank is unreliable.
02 Rational Man and Animal Spirits
"It is better to make mistakes with the crowd than to be right alone." This is one of the phenomena that impressed me most in 2022. In 2021, people collectively believed that buying a house was a good investment. Until March 2022, people collectively believed that buying a house was a dangerous thing. This change is surprising. In my articles and video programs in April this year, I encouraged everyone to continue buying houses, but I was labeled unscrupulous by some people. I can’t see any difference between buying a house in February and April. Until July, the borrowing capacity for mortgage loans dropped significantly. People still couldn’t understand such a simple fact: since the decline in house prices was caused by an interest rate increase, the interest rate increase can also cause a decrease in borrowing capacity. In which month you buy a house, your down payment and monthly payment will wax and wane with the interest rate. As house prices fall, the down payment will be less, but as the interest rate rises, the monthly payment will increase. For the same family, there will be little change. By the end of the year, people finally understood, but were unwilling to admit, that the decline in borrowing ability was greater than the decline in prices of some properties. People who could have bought a car from February to July unfortunately missed the opportunity because of fear.
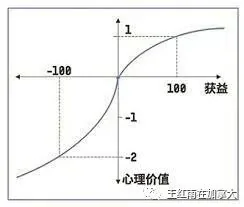
The so-called "rationality" refers to the "calculation" that can clearly understand the pros and cons, and those who miscalculate are irrational people. The phrase "animal spirits" was first used by Keynes, but one of the people who learned about animal spirits was the famous Newton. He said very early on, "I can calculate the trajectory of celestial bodies, but I cannot calculate the madness in people's hearts." The research on animal spirits in investment has made great progress in recent years. Nobel Prize winner in economics and psychologist Daniel Kahneman showed after studying people’s behavioral psychology that not only people’s madness cannot be calculated, but their fear is also uncalculated. Kahneman reluctantly gave a rough number, fear is 2.5 times greater than greed. That is, if you are invited to participate in a gambling game and you lose 1 yuan if you lose and get 2.5 yuan if you win, only then will someone be willing to place a bet. Kahneman calls this irrationality “loss aversion.” When housing prices are falling, people regard housing prices as a falling knife. If they don't catch it well, they will hurt themselves. But they forget that after the knife falls, they may not be able to grab it.
In 2021, of the 100,000 second-hand housing transactions in the GTA and Greater Toronto Area, 36,000 were supported by shadow banks and private lending. This ratio is unprecedented. Only 2/3 of buyers passed the stress test of major banks and obtained loans from major banks. Only when people are extremely fanatical will they borrow high-interest loans to buy a house, completely regardless of the fact that these loans are short-term contracts and what they buy is an asset that needs to be held for a long time. It can be seen how crazy the atmosphere is for buying a house in 2021. On the contrary, before July 3, 2022, the stress test interest rate will be the same as in 2021. People who were able to get loans to buy houses last year will also be able to borrow loans from big banks to buy houses in the first half of this year. Unfortunately, many people are controlled by fear, completely unable to move, and completely unable to listen to rational analysis. From August to November, house prices gradually stabilized, but after people's fear was relieved, they discovered that their borrowing capacity had dropped significantly.Fear is an instinct developed by humans from the hunting period, and it is also an important characteristic of self-protection. However, fear is a cost in investment, not a benefit. No one profits from fear. Fanaticism is a kind of passion, especially among people who are easily infected. It is not an instinct, but more like an infectious disease. Fanaticism is the main cause of losses.
Buffett said, "I am greedy when others are fearful, and fearful when others are greedy." We, the general public, are the "others" he refers to. Reflecting on ourselves, we really cannot be calm and rational as Buffett said, so we are still ordinary beings. Now, we are not only faced with the problem of "cannot do it", but more seriously, the entire foundation of economics is based on the "rational man hypothesis". If we cannot be rational, then the textbooks will be in vain, because we understand the principles, but cannot guide actions. The reason why behavioral economics has received attention in recent years is that this branch recognizes that people's rationality comes and goes, and that people's animal spirits are difficult to overcome. From the phenomena observed in 2022, the results of my own thinking are:People must have a long-term plan for their financial goals. Ordinary people of flesh and blood cannot be rational all the time. We must accept this weakness. Only by setting a long-term goal and constantly working towards a goal can we overcome the interference caused by fear and greed.If you set real estate investment as an unreliable goal to fight against Leviathan, as a long-term investment goal to fight against the continuous depreciation of currency purchasing power and achieve a balanced lifetime income, don't change the goal casually. Thinking that real estate is worth investing in when house prices are rising and abandoning it like worn-out shoes when house prices are falling is a speculator's approach and is not suitable for long-term investment. I believe that the behavioral patterns of passive investors need to be corrected, and I also understand the troubles that instinctive fear causes to investors.
In fact, from 2018 to now, the road of real estate investment has been bumpy. In 2018, the stress test interest rate was raised, and interest rates were raised throughout the year; in 2019, the shadow of the recession became larger and larger, and the stock market was in a haze; in 2020, the epidemic broke out, and rents dropped sharply; in 2021, speculators entered the market in large numbers, raising the cost of buying a house. In 2022, the policy took a sharp turn, high inflation and high interest rates, leading to a gloomy market. Even during these five uneventful years, some of my clients have still achieved the accumulation goal of multiple houses. One of the couples is already considering retiring seven years in advance. Our private banking account manager is helping them calculate whether the cash flow will support their post-retirement life if one retires. Early retirement is the highest reward for those who work hard and file their taxes honestly. An ordinary IT dual-career family, with no background in economic theory, worked hard to accumulate real estate in just 5 years, did not listen to the noise, and did not regard "legal tax avoidance" as the most important thing in investment. They just took action after listening to one of my lectures 5 years ago. To be able to achieve such results makes me feel that everything I have done is worthwhile. I am proud to serve such a family. I think the most important reason why they achieved their goals so quickly is not timing, high income, or luck, but because they set long-term investment goals and put them into action.Canada has a chronic mismatch in monetary policy, housing policy and immigration policy that will lead to a housing crisis in the futureIt cannot be solved in 30-50 years. This length of time is enough for families interested in real estate investment to buy and hold multiple properties for a long time and retire early and safely.Real estate investors, if you want to achieve financial security in most areas, it will not take too long, but you need to stick to your long-term goals without slacking off, without hesitation, not half-heartedly, and not follow the crowd. Come on, readers.
03 Pull out the flowers and water the weeds
In February and March this year, there was a popular theory of "escape from the top". By selling investment properties after retirement, you can maximize your profits, hold the property for a long time, spread transaction costs, and obtain housing crisis dividends as much as possible. Families who believe in the theory of escaping from the top will have difficulty finding better alternative investments throughout 2022, even if they successfully achieve their goals. Depositing the house sale money into GIC is equivalent to pulling out the flowers and watering the weeds.
The certainty of real estate investment returns comes from the long-term unsolvable contradiction between population growth and the speed of new housing construction. Even if people generally believe that there is a housing price bubble, it cannot be denied that there is indeed not enough housing. When the new population matches the number of newly built housing, the dividends from real estate investment will disappear. In other words, before the housing crisis is resolved, the opportunity cost of investing in assets other than real estate is the income from investing in real estate. After the demand for buying houses was suppressed, rents increased significantly, which shows that the housing crisis exists objectively. The increase in rents is to digest the housing price bubble and make the ratio of housing prices and rents more reasonable. Areas with excessive house price bubbles are being deleveraged by the effect of interest rate hikes. In some areas of the GTA, this debubble is being de-bubbled very hard. It is reasonable to escape from the top in areas with the largest bubbles, but which areas have the largest bubbles can only be known afterwards. Foreknowledge is difficult to achieve. If you miss the mark, you may never be able to buy back the property you sold, and you may be downgraded due to selling too early.
When house prices rise sharply and the bubble becomes large, the best thing to do is not to sell the house, but to borrow money from the high house prices to get cash from the high house prices. In March 2017, I suggested to a colleague to increase the mortgage on his own house in NEWMARKET, cash it out as a down payment, buy a second house, and keep the original house as an investment house. When I suggested it, the market price of the house was 1 million. Four months later, my colleague told me that because I didn’t act immediately, the house price was already 800,000 when I went to appraise it, and I couldn’t cash it out. Five years have passed, and I am still living in that home.There is a time to make the leap from homeowner to landlord, and everyone's time is different. When housing prices rise and you have the ability to increase your mortgage, it is time for a jump in wealth., rather than asking someone to figure out where the value is and when is the right time to buy a house. No one knows when you should buy a house.The timing of buying or upgrading a house varies from person to person. This timing is exclusive and occurs when you can add a mortgage on the property.There are too few people who understand this truth.
February and March of this year are the most suitable for raising mortgages and are a great time to make a class jump. However, 95% of people have backed down because the flames of interest rate hikes have been vaguely visible and fear has enveloped the market. A few people have done the opposite, pulled out the flowers and started watering the weeds. Based on the experience and lessons learned by my colleagues in 2017, I still publicly expressed my thoughts until April, not to sell the house, but to increase the mortgage, but there are not many people who are not controlled by fear.
04 Professional opinions and hearsay about you
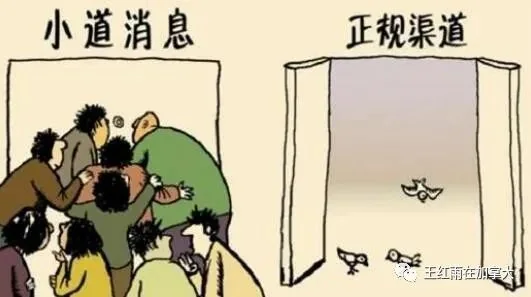
Real estate and loan brokers say that real estate investment is the best, with guaranteed profits without loss; stock brokers say that financial asset investments are the best because of strong liquidity; insurance brokers say that insurance also has investment and insurance functions; accountants say that legal tax avoidance is of top priority. This is the real environment we are facing now. Professionals all need to make money to support their families, so they all boast about themselves. Only when professionals are regarded as sailors on Noah's Ark of wealth and become captains themselves, will this small boat have a direction, a purpose, and a timetable, instead of letting the sailors row the boat around and never reach the destination.
2022 is a time window for reinvestment. Stock prices, house prices and bond prices are all falling. Many people have huddled in GIC and are completely afraid to invest. Although the Internet makes information cheaper and faster to spread, the cost of screening information is getting higher and higher. For any statement, theory, or suggestion, you can find its opposite, theory, or suggestion. This year, there has been a great conflict of concepts and ideas. It is a good time for us to analyze and reflect on this issue.
Secondly, opinions and services that cater to your ideas may not necessarily be suitable for you. In 2021, many people recommend increasing mortgages on their own homes and cashing out to buy investment properties. Because the prerequisite for early retirement is that the owner-occupier has no mortgage, such advice is completely contrary to the goal of early retirement. However, such suggestions catered to the ideas of some people and were adopted. You need to judge whether the advice from professionals is in line with your long-term goals.
Third, free advice cannot be tailored to your special situation, so take care of yourself. During the epidemic, many people asked about the choice of loan interest rates. I answered that when investing in housing, choose floating interest rates. Some people took this free advice and applied for home loans from other banks. After interest rate increases began, their monthly payments increased every time the interest rates increased. Our bank's floating interest rate will keep the monthly payment unchanged after interest rate increases. The increased interest payments on investment properties can be tax deductible. The advice I give is of course for our bank's loan products. I don't suggest you apply for a loan from other banks, nor do I say you should choose a floating interest rate for your own home. Many people complain about the world and the air after a problem occurs, but they just don't reflect on themselves, why they don't consult one-on-one for the solutions they need.
Fourth, a lot of contradictory advice comes from contradictory investment goals. Howard Marks said in an exclusive interview that when someone asks him for investment advice, he will ask the person, do you want asset appreciation or preservation of value? The host was very surprised and asked him, is there a difference? Howard said, of course, value preservation and value appreciation are two completely different things, and they cannot be both, so the advice is also completely different. Legally maximizing tax avoidance and maximizing loan amounts are incompatible and opposite goals, so the advice is exactly the opposite. If tax saving is the first priority, the loan to buy a house will be restricted, so the asset growth rate is extremely slow. In most cases, it will take a lifetime to be accompanied by financial anxiety.
Fifth, investment losses occur because the captain is incompetent and has little connection with the sailors. Remember, professionals are just sailors and tools, not captains and masters of tools. Different opinions in different professional fields are precisely tools for investors to enrich their thinking and break out of the information cocoon. Every professional has professional limitations and self-interest bias. Those who only have a hammer in their hand will see everything as a nail. As an investor, you need to carry a toolbox in your hand, not just a hammer.
Conclusion:
While 2022 is not over yet, we sum up our experiences and lessons on the spot, and let Internet memory help us remember this unforgettable year. History does not simply repeat itself, but the rhymes are the same. 2022 is very much like 2018, and looking back at 2018, it is a very good time window for real estate investment. This year we have seen more clearly the influence of the central bank on us, and experienced the real existence of Leviathan with our own skin. Answer yourself honestly: In this year, are we a brainless sheep in the flock, or a lone warrior who dares to go against the grain? Are you moving firmly toward your long-term goals, or are you overcome by fear? During turbulent times, have you ever been so frightened that you pulled up flowers and watered weeds? Have you ever respected the professional opinions of professionals? Do you honestly regard yourself as the captain of Noah's Ark, identifying and dispatching your own crew? Everyone has their own 2022. If you have valuable experiences or lessons worth remembering and want to share them with other readers, please leave a message after the article.
When Confucius praised his disciple Yan Hui, he used six words: "Don't express anger, never make mistakes." The best quality of a learner is: not to anger others when he makes a mistake, and not to make the same mistake twice. Each of us is on the road to learning investment, and you are not alone. Making mistakes is not terrible, but anger is terrible. What cannot be tolerated is not making mistakes, but making the same mistakes repeatedly. On this occasion, I wish all readers good health and fruitful investment. In January next year, I will give you the investment outlook for 2023. We will see you on the official account next year.